
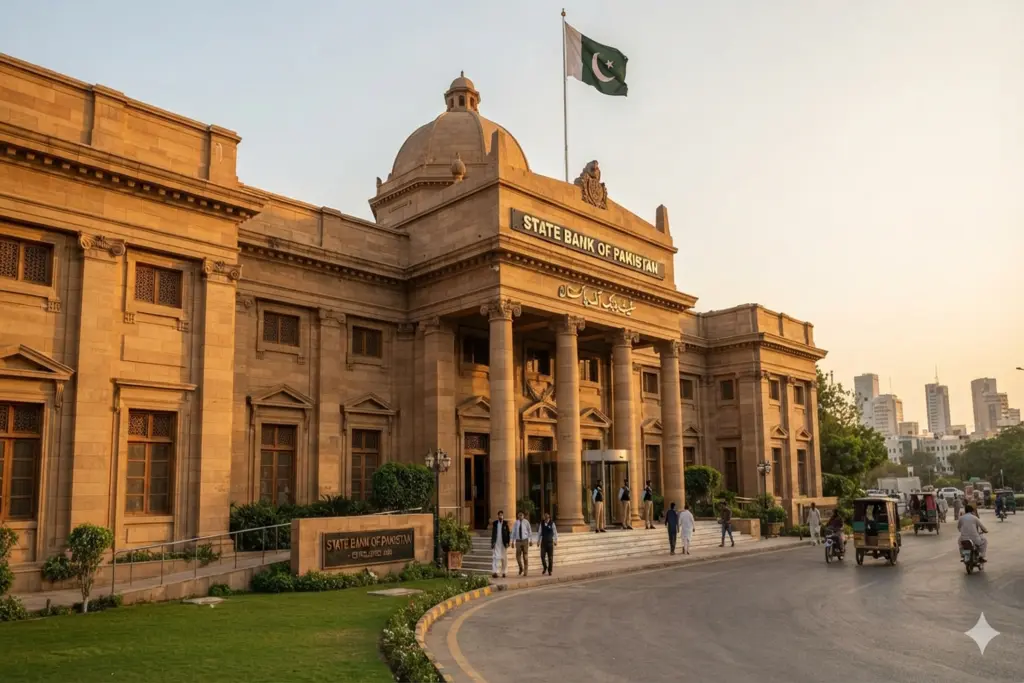
The State Bank of Pakistan (SBP) has officially announced the introduction of SBP Financing Framework that is going to bring a paradigm shift in the credit facilities offered to small enterprises and small farmers. This new structural mechanism enables commercial banks to provide credit lines via wholesale and agency arrangements, using local financial networks. The central bank seeks to greatly expand loan dispersion under the federal government’s active Risk Coverage Facility through the smaller intermediaries.
Authorized Intermediaries and Lending Limits
With this automated system, eligible microfinance banks, non-bank microfinance companies or non-bank financial companies (NBFCs) can enter into a legal relationship with commercial banking institutions. These designated representatives will have direct control over the most important processes such as loan origination, risk assessment, final approval, tracking, and recovery. All loans disbursed will be transparently documented on the books and through real-time API based software integration from the main banks to the field banks to ensure systematic tracking.
The central bank has set up strict corporate and agricultural credit ceilings depending on the type of intermediary institution used:
Small Enterprises: Capped at Rs. 1 million per borrower for non-bank microfinance companies, and up to Rs. Rates for NBFCs and Microfinance Banks are 5 million.
Agricultural Borrowers: Cap of Rs. 500,000 for non-bank microfinance companies, reaching up to Rs. Total disbursement at NBFCs and specialized microfinance banks will reach 2 million.
Strict Eligibility Criteria for Partner Institutions
The State Bank of Pakistan has built in strong compliance standards for their participants to ensure financial sustainability and safeguard public funds. Partner institutions are required to have 100 percent operational self-sufficiency, and their existing SBA and agriculture small business and agriculture portfolios must have a maximum non-performing loan (NPL) ratio of 5 percent.
In addition, the candidate institutions must have unqualified audit opinions for the last two fiscal years, experience in enterprise lending for at least three years and fully meet all regulatory requirements on capital adequacy. An absolute compliance with the national anti money laundering (AML) and counter terrorism financing (CTF) regulations continues to be mandatory under the supervision and control of SBP and Securities and Exchange Commission of Pakistan (SECP).
Who Qualifies as an Authorized Intermediary Under the Plan? Look into the strict institutional benchmarks requiring operational self-sufficiency and low non-performing loan ratios.
Why Was the API-Based Integration Mandated by the Central Bank? Find the technical explanations behind ensuring that all distributed credits are fully identifiable and traceable online.
Which Financial Caps Apply to Small Agricultural Borrowers? Dive into the specific lending limits established for non-bank microfinance companies and microfinance banks.
How Does the Federal Risk Coverage Scheme Protect Partner Banks? Uncover the government backing designed to secure commercial portfolios focused on rural growers and small enterprises.
Where Can Eligible Microfinance Entities Review Compliance Regulations? Check out the central banking directives published online alongside secondary oversight updates from the SECP.